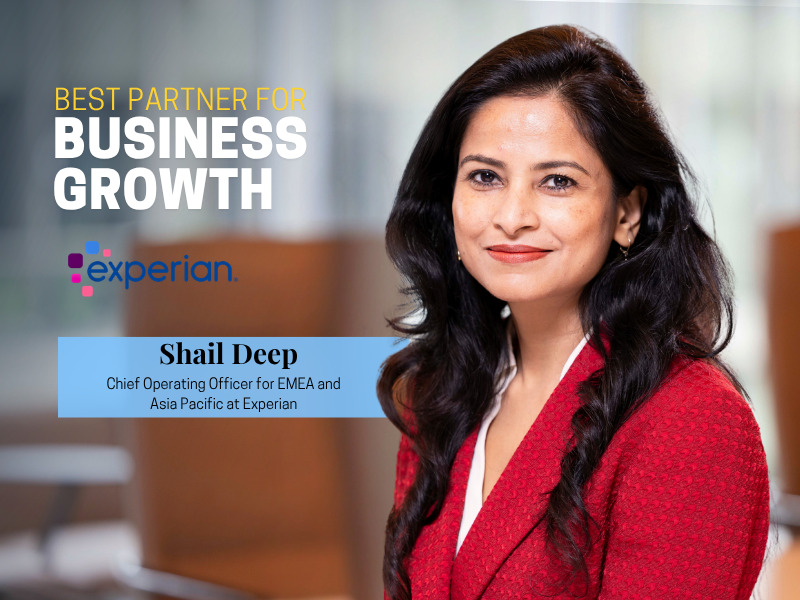
Interview with Shail Deep of EMEA & APAC at Experian
That AI is vital to business operations is no longer in question. How AI is deployed, scaled, and governed will determine whether it delivers meaningful value.
After a quarter of a century spent across retail banking and technology consulting, Shail Deep, Chief Operating Officer at Experian EMEA and Asia Pacific, sits smack at the intersection of financial services, organisational processes, and technology. She sat down with EBR to discuss AI adoption in businesses and the question increasingly confronting organisations: how do they move from experimenting with AI to deploying it at scale, while ensuring it delivers meaningful value and remains accountable?
With almost 25 years in financial services and technology, you have witnessed several major shifts in how businesses operate. Was there a particular experience that changed the way you lead, and what has stayed with you from it?
One thing I have learnt is that transformation rarely fails because people lack ambition. Rather, it becomes difficult when strategy meets execution. I have worked through several major technology shifts, across different organisations and markets, and what has stayed with me is the importance of understanding the problem before becoming attached to the solution. Technology changes incredibly quickly. The fundamental questions change much less: what are we trying to improve, who will benefit, and can we make it work reliably at scale?
A brilliant idea in isolation has limited value if the organisation cannot operationalise it.
That has shaped how I lead today. I spend a lot of time thinking about the connections between people, processes and technology. A brilliant idea in isolation has limited value if the organisation cannot operationalise it. I have also become more comfortable with experimentation. You need to give people permission to test ideas, learn quickly and sometimes stop something that is not working. But experimentation needs discipline. You have to know what success looks like before you begin. That combination has stayed with me: be ambitious about what technology can enable but be very practical about what it takes to deliver.
Many AI ideas appear promising during an initial trial. What evidence tells you that an experiment is solving a meaningful problem and is ready to move into everyday operations?
For me, the first test is very simple: has it solved a real problem? A successful demonstration is not the same as a successful business outcome. Before moving an AI experiment into everyday operations, I would want evidence in three areas.
One, does it measurably improve an outcome that matters? That could be reducing the time required to make a decision, improving accuracy, helping employees work more effectively, reducing fraud, or improving a customer’s experience. Two, does it continue to perform outside the controlled environment of the pilot? Real operations introduce different data, customers, systems, edge cases and behaviours. Three, can we operate it responsibly? That means understanding the data being used, how the output is generated, how performance will be monitored, who is accountable, and when a human needs to intervene.
That last step is important. Our Connected Intelligence research shows that 68% of financial institutions remain at an early or emerging stage of AI adoption. The challenge now is less about demonstrating that AI works and increasingly about creating the conditions in which it can work consistently. At Experian, that is why we tie AI investments to tangible, measurable impacts rather than adopting technology simply because it is new.
Experian’s Connected Intelligence research suggests that an AI project may succeed in one part of a business but struggle when applied more widely. What capabilities, structures, or cultural conditions must be in place before an early success can scale across an organisation?
Scaling AI is fundamentally an organisational challenge, not just a technology challenge. An experiment can succeed within one team because the people know the data, understand the exceptions and can work around limitations manually. At enterprise scale, those workarounds disappear very quickly. You therefore need several things working together.
You need to have trusted and accessible data. You need systems that can communicate rather than operate as isolated islands. You need governance embedded into the workflow, with clear accountability for decisions and outcomes. And you need people who understand both the technology and the business process that it is changing.
Culture matters just as much. Teams need to be willing to share what they have learnt, including what did not work. Leaders also need to avoid creating dozens of disconnected AI projects solving variations of the same problem.
Our research also found that only 11% of financial institutions have extended AI into core environments at scale. That tells me the next competitive advantage will not necessarily come from having more AI pilots. It will come from becoming better at connecting successful experiments to the organisation around them. I often describe innovation as moving from episodic to systemic. When the underlying system is right, good ideas become much easier to scale.
AI is only as effective as the information behind it. When data and organisational knowledge are fragmented across teams and systems, what should leaders prioritise fixing first?
I would say start with the decision you are trying to improve, not with an ambition to fix every piece of data in the organisation. Most large businesses have accumulated different datasets and processes over many years. So, begin with the decision or business problem you are trying to improve, then work backwards through the data that supports it. Trace the information required for an important decision from beginning to end. Where does the data originate? Is it accurate? Who owns it? Can the relevant systems access it at the right time? Is its use appropriately governed? And can you understand why the resulting decision was made? That exercise can quickly expose the fragmentation that matters.
Globally, 62% of financial institutions agree that data quality and governance are contributing factors in AI deployment failure.
Our Connected Intelligence research reinforces this point. Globally, 62% of financial institutions agree that data quality and governance are contributing factors in AI deployment failure. So, I would prioritise making data trusted, connected and usable at the point of decision. More data does not automatically produce better AI. Better quality and contextual data does. That is particularly important in financial services, where the quality of a decision can affect someone’s ability to access credit, protect themselves from fraud or manage their financial life.
AI is increasingly moving beyond providing information towards influencing, or even making, important financial decisions. How should organisations decide how much responsibility to give AI and where human judgment must remain essential?
The level of autonomy should reflect the consequences of the decision. There are many situations where AI can take on significant responsibility. It can process enormous volumes of information, identify patterns that would be difficult for people to see and support faster, more consistent decisions. But capability alone should never determine authority.
As the potential impact on a person increases, the requirements around explainability, oversight and accountability should increase with it. This can be viewed as a spectrum rather than a binary choice between humans and machines. At one end, AI can automate repetitive, low-risk tasks. In the middle, it can make recommendations while a person retains decision authority. At the other end are consequential or unusual decisions where human judgment remains essential. The objective is not to preserve human involvement for its own sake. It is to put judgment where judgment adds value.
The strongest model is augmentation: machines bringing speed, consistency and analytical capacity, with people bringing context, empathy and accountability. That has been a consistent principle in how we think about AI at Experian.

As AI assumes greater responsibility, questions of trust and accountability become more urgent. What must organisations do to earn customers’ trust and ensure that responsibility remains clear when something goes wrong?
Trust has to be designed into the operating model. It cannot be added afterwards as a communications exercise. In business credit risk assessment, where explainable machine learning can support important decisions, organisations need to be able to understand and explain how those models are being used, what information is informing the decision and what happens if a decision needs to be reviewed.
Internally, accountability must be equally clear. An organisation cannot say, “the algorithm made the decision”. There must always be ownership of the system, the data, the controls and ultimately the outcome. That requires governance throughout the lifecycle: how models are developed and validated, how data is used, how bias and performance are monitored, how exceptions are handled and how issues are escalated. This is particularly important in credit risk, where explainability and appropriate human oversight help businesses make more informed decisions while maintaining clear accountability.
Experian operates across markets with different regulations, customer expectations, and levels of digital maturity. What has this taught you about introducing AI at scale while remaining responsive to local needs?
One of the biggest lessons from operating across EMEA and Asia Pacific is that markets have much more in common than they do differences when it comes to the foundations required to scale AI. Security, responsible data use, appropriate governance, explainability and clear accountability matter wherever you operate.
Where differences emerge is in how those principles are applied. Regulation, customer expectations, available data, and levels of digital maturity vary by market, so implementation needs to reflect the local context.
The organisations that scale AI successfully will be those that can standardise what should be common without standardising away local insight.
We see that diversity throughout our region. In some markets, alternative data can help address limited traditional credit histories. In others, sophisticated digital ecosystems create opportunities for real-time decisioning or fraud prevention. The regulatory detail may differ, but the underlying need for trusted data, effective governance and accountable decision-making is remarkably consistent.
The model I believe in is therefore global capability with local relevance. Build common platforms, standards and governance so that you benefit from scale, but give local teams enough flexibility to solve the problems that matter in their markets. We have seen that approach across our own region, from digital onboarding in Italy and fraud detection in Germany to alternative data and advanced analytics in South Africa.
The organisations that scale AI successfully will be those that can standardise what should be common without standardising away local insight.
Looking ahead, what excites you most about AI’s potential to reshape business and financial services, and what risks do you think leaders may still be underestimating?
What excites me most is the possibility of making complex systems much more responsive to individual circumstances. Financial services has traditionally depended on relatively standardised processes. AI, combined with better data, gives us the opportunity to understand context much more effectively. That can mean helping a lender assess somebody with a limited traditional credit history, identifying fraud without introducing unnecessary friction for genuine customers, or giving people more personalised support in managing their financial lives.
At Experian, we have a suite of assistants based on LLMs that help data scientists and fraud prevention investigators use our software more efficiently. Then our Agent Operating System (AOS) is a trusted agentic AI layer launched in June 2026 within the Ascend Platform to help businesses safely scale autonomous AI across the lending lifecycle.
That is why I remain optimistic, but deliberately so. The opportunity is substantial, particularly if AI can help us make financial services faster, more inclusive and more responsive. But the organisations that create lasting value will not necessarily be those that move fastest. They will be those that combine innovation with the strong governance, human judgement and the operational discipline required to earn trust at scale.