By Colin Horan
I’m Colin Horan, one of Ireland’s leading property experts. As someone who has navigated the Irish property market for over two decades, I’ve witnessed numerous boom and bust cycles, policy shifts, and market corrections. However, what we’re experiencing in Ireland’s property sector today represents something markedly different from previous surges. The current escalation in property prices isn’t simply a case of market overheating or speculative frenzy—it’s the result of a perfect storm of structural, economic, and demographic factors that have converged to create unprecedented pricing pressures.
From my vantage point working directly with buyers, sellers, and investors across the country, I can tell you that the frustration is palpable. First-time buyers are being priced out of markets they grew up in, whilst families seeking to upgrade find themselves trapped by affordability constraints. Yet understanding why prices are soaring is the first step towards navigating this challenging landscape. In this article, I’ll break down the key drivers behind Ireland’s property price surge and offer insights into what this means for stakeholders across the market.
The Housing Supply Crisis: A Decades-Long Deficit
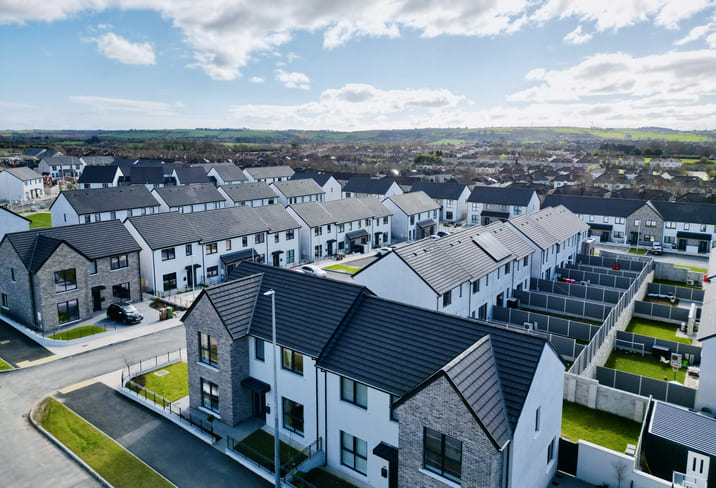
The most fundamental driver of Ireland’s soaring property prices is devastatingly simple: we’re not building enough homes. Following the 2008 financial crash, construction ground to a virtual standstill. An entire generation of tradespeople left the industry, planning departments were gutted, and the development sector—traumatised by widespread failures—retreated dramatically.
Whilst we needed approximately 35,000 to 40,000 new homes annually to meet demand, we’ve consistently fallen short of this target. Between 2010 and 2015, annual housing completions averaged just 8,000 units. Although production has increased in recent years, we’ve never fully recovered to the output levels required to address both current demand and the accumulated deficit from the previous decade.
I’ve watched as development sites that should house hundreds of families remain vacant or underutilised. The reasons are manifold: planning delays, infrastructure deficits, skilled labour shortages, and construction cost inflation. Each of these factors compounds the others, creating a vicious cycle that suppresses supply whilst demand continues to surge.
The mathematics are stark. Ireland’s population has grown significantly, yet our housing stock hasn’t kept pace. This fundamental imbalance between supply and demand creates the perfect conditions for price escalation—and that’s precisely what we’re witnessing.
Construction Costs: The Hidden Price Driver
A factor often overlooked in public discourse is the dramatic escalation in construction costs. As someone who regularly reviews development appraisals and feasibility studies, I can attest that building homes in Ireland has become extraordinarily expensive.
Material costs have surged dramatically, particularly post-pandemic. Timber prices at one point doubled within months. Steel, concrete, and insulation materials have all experienced significant price increases. These aren’t temporary blips—many of these elevated costs have become entrenched in the market.
Labour costs have similarly escalated. The shortage of skilled tradespeople—electricians, plumbers, bricklayers, and carpenters—has created intense competition for workers, driving wages upward. Whilst I’m absolutely supportive of fair compensation for skilled labour, this does translate into higher development costs, which inevitably flow through to end purchasers.
Furthermore, regulatory requirements, whilst important for quality and safety, add layers of cost. Building Energy Rating (BER) standards, fire safety regulations, and accessibility requirements all necessitate additional investment. A modern apartment building must meet standards far exceeding those of properties built even a decade ago.
When I calculate the all-in cost of delivering a new home in Dublin or Cork, it’s often north of €350,000 to €400,000—and that’s before the developer’s profit margin. This creates a floor beneath which prices simply cannot fall, regardless of market conditions.
The Demand Side: Multiple Cohorts Competing for Limited Stock
Ireland’s demand profile has become increasingly complex, with multiple buyer cohorts competing simultaneously for the same limited housing stock.
First-time buyers, many of whom have been saving for years, represent substantial pent-up demand. This cohort has grown as people delayed purchasing during the pandemic, creating a demographic bulge of would-be homeowners now seeking to enter the market.
Simultaneously, downsizers and upgraders—families seeking additional space, particularly post-pandemic when working from home became normalised—are actively competing in the market. I’ve had countless conversations with clients whose needs have fundamentally changed, making their current accommodation unsuitable.
The investor segment, whilst somewhat constrained by regulatory measures, remains active. The rental market’s strength makes residential property an attractive investment proposition, particularly for pension funds and institutional investors seeking long-term stable returns.
We’re also seeing returning emigrants and international buyers, attracted by Ireland’s economic performance, political stability, and quality of life. The growth of multinational corporations in Ireland has created substantial demand from relocating professionals.
All these groups are competing for the same finite housing stock. In desirable locations, it’s not uncommon for properties to receive multiple offers within days of listing. I’ve witnessed bidding wars that push final sale prices 10% to 15% above asking—a clear indication of excess demand over supply.
The Inflation Factor: Money, Interest Rates, and Asset Prices
The broader macroeconomic environment has played a significant role in property price inflation. The extended period of ultra-low interest rates, whilst now reversing, made borrowing exceptionally cheap for nearly a decade. This increased purchasing power and enabled buyers to bid more aggressively for properties.
When mortgage rates were hovering around 2% to 3%, buyers could service substantially larger loans than when rates sit at 4% to 5%. This monetary environment inflated asset prices across the board, with property being a primary beneficiary.
Additionally, general inflation has eroded the purchasing power of money. The property market doesn’t exist in isolation—when the cost of everything from groceries to petrol increases, property prices tend to follow. From my perspective, some of what appears to be property price inflation is actually currency devaluation manifesting in asset prices.
The pandemic-era money printing and fiscal stimulus measures injected enormous liquidity into the economy. Much of this capital has sought refuge in tangible assets, including property. I’ve noticed a marked increase in cash buyers and those with substantial deposits—evidence of accumulated wealth seeking deployment.
Regulatory and Taxation Measures: Unintended Consequences
Government interventions, whilst well-intentioned, have occasionally produced counterproductive outcomes. The Help to Buy scheme, designed to assist first-time buyers, arguably inflated prices by increasing purchasing power without addressing supply constraints. When all buyers can bid more, prices simply rise to absorb that additional capacity.
Rental regulations, including rent pressure zones and eviction restrictions, have made some landlords exit the market entirely. I’ve worked with numerous small-scale landlords who’ve decided to sell rather than navigate increasingly complex regulatory requirements. This has reduced rental supply, increasing rents, which in turn makes property investment more attractive on a yield basis—supporting higher capital values.
The Central Bank’s mortgage lending rules, whilst prudent from a financial stability perspective, have created a two-tier market. Those with access to parental assistance or existing equity can compete effectively, whilst those relying solely on mortgage financing face hard constraints. This hasn’t suppressed prices; it’s simply changed who can participate.
Vacant property taxes and zoned land taxes are recent additions aimed at bringing unused land and properties into productive use. Whilst these may have positive long-term effects, their short-term impact on supply has been minimal, and they may actually increase holding costs that get passed through to purchasers.
Regional Variations: Not All Markets Are Equal
It’s crucial to understand that Ireland’s property market isn’t monolithic. Dublin, Cork, Galway, and Limerick have experienced more pronounced price increases than rural locations. Proximity to employment centres, infrastructure, and amenities drives localised demand spikes.
I’ve observed that commuter belt locations have seen particularly dramatic price escalation as buyers seek affordability whilst maintaining employment access. Towns within an hour of Dublin or Cork have become pressure points, with prices climbing as buyers are displaced from urban centres.
Conversely, some rural locations have seen modest price growth or even stagnation. Depopulation, limited employment opportunities, and ageing housing stock in certain areas creates very different market dynamics. A blanket national policy response fails to account for these regional disparities.
Looking Forward: What Does This Mean for the Market?
Based on my assessment, several factors will shape the property market’s trajectory over the coming years. Supply will gradually improve as current construction projects complete, but this will be a slow process. We’re years away from equilibrium between supply and demand.
Interest rates have risen and may remain elevated, which will constrain some buyers’ purchasing power. This should apply downward pressure on prices, though supply constraints may limit any correction.
Build-to-rent developments and increased density in urban areas represent potential supply-side solutions, though these won’t address detached and semi-detached family home demand, which remains acute. Due to this, we have seen a drastic increase in attic conversions as an alternative to building an extension or buying a second larger home.
Ireland’s property price surge isn’t the result of a single factor but rather the convergence of chronic undersupply, elevated construction costs, robust demand from multiple cohorts, favourable financing conditions, and occasionally counterproductive policy interventions. Having worked through multiple market cycles, I can say with confidence that this represents a structural challenge requiring sustained, multifaceted responses.
For prospective buyers, understanding these dynamics is essential for making informed decisions. For policymakers, addressing the supply deficit must remain the paramount priority. Whilst demand-side measures may provide temporary relief, only substantially increased housing delivery will fundamentally resolve Ireland’s property pricing crisis. The path forward requires patience, strategic planning, and realistic expectations about the timeframes required to rebalance this market.
Disclaimer: This article contains sponsored marketing content. It is intended for promotional purposes and should not be considered as an endorsement or recommendation by our website. Readers are encouraged to conduct their own research and exercise their own judgment before making any decisions based on the information provided in this article.


