
By Dr Nikhilesh Sinha and Satrupa Ghosh
Although Europe has the highest number of circular startups1 and its cities lead on circular transition plans, coordination is often sorely lacking.
While European entrepreneurs are building businesses designed to keep materials in use and close the loop between production and consumption, and European cities are redesigning their infrastructure to drive the same transition, these two powerful forces are acting largely out of synch. Nikhilesh Sinha and Satrupa Ghosh of Hult International Business School assess the consequences and discuss what cities can learn from each other in helping circularity to flourish.
Europe’s Circular Aspirations
The EU’s Copernicus Climate Change Service recorded that average temperatures between 2023 and 2025 were the warmest ever measured. The summer of 2026 has seen four heat waves and wildfires scorching across Southern Europe. Cities are where the temperatures and the stakes are highest. They generate four-fifths of global GDP but account for 70 per cent of global greenhouse gas emissions.2 With urban populations set to double by 2050, the pressure on urban resource systems will only intensify.
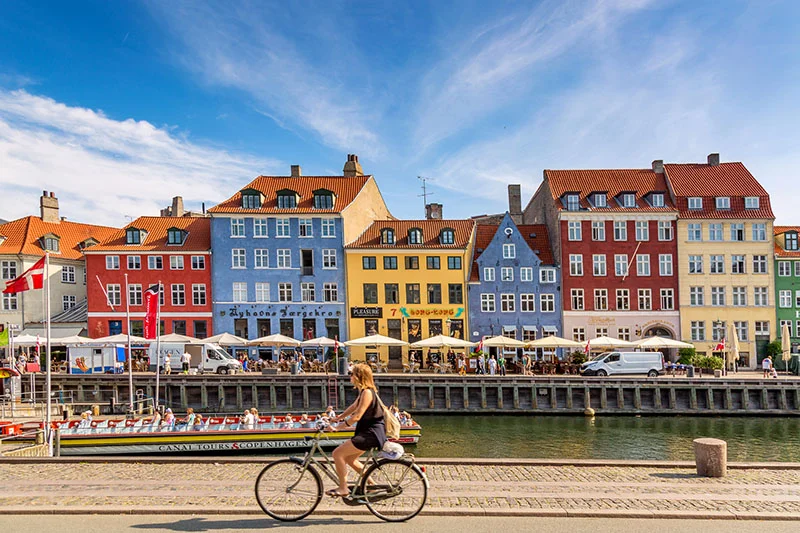
Across the continent, cities are trying to hard-wire circular logic into urban systems. Amsterdam has committed to halving its use of virgin materials by 2030 and reaching full circularity by 2050, with a growing emphasis on tracking material flows. Copenhagen is pairing climate ambition with practical redesign, from standardising sorting of household waste into 10 different categories, to scaling the infrastructure for sorted waste across the city. London has positioned itself as a circular leader, with a Circular Economy Route Map that targets high-impact sectors including textiles, plastics, food, electronics, and the built environment. These programmes signal that circularity in Europe is no longer a niche environmental agenda. It is being treated as a city-building project – redesigning how materials move through dense, service-heavy economies, and how urban governance enables reuse, repair, and recovery at scale.
These programmes signal that circularity in Europe is no longer a niche environmental agenda. It is being treated as a city-building project.
Europe also boasts the highest number of emerging circular enterprises, around 2,800, most of which emerge out of Germany, France, and the UK3. These are businesses whose entire model is built around circularity from the outset, rather than treating it as an add-on to an existing operation. Aachen-based Voltfang gives second-hand electric vehicle batteries a second life, converting decommissioned car batteries into stationary energy storage systems. It has repurposed over 6,900 battery modules and opened what it describes as Europe’s largest second-life battery factory in 2025.4 Too Good To Go, founded in Copenhagen in 2016, has built the world’s largest marketplace for surplus food, connecting consumers with restaurants and retailers to rescue unsold meals. Since launch, it has saved over 500 million meals from waste across 21 countries.5 Amsterdam’s Fairphone designs modular smartphones built for repair and longevity, with every component replaceable by the user, and is on track to surpass one million devices sold since founding. Their business model challenges the use-and-throw business model which contributed to five billion phones becoming e-waste in a single year.6
Yet the city-level plans and the startup-level strategies don’t connect, creating a circularity gap, but also an opportunity. The question is whether they can co-create the shared infrastructure, governance, and material loops that can help both cities and businesses scale their circular ambitions.
Mind the Gap: Lessons from London
London offers a cautionary tale. Rated the world’s most circular city in 2024 by the Holcim-Bloomberg Circular Cities Barometer, it has committed to net zero a decade ahead of the rest of the UK, with its Circular Economy Route Map targeting textiles, food, plastics, electronics, and the built environment as priority sectors.7 It is also one of the world’s great fashion capitals, though that distinction sits uneasily alongside its circular ambitions. The average Londoner buys one garment a week, and the textile sector generates over two million tonnes of greenhouse gas emissions annually, with around 17 per cent of all emissions linked to goods consumption in the city.8
Our research examined three circular fashion startups, each pioneering a different model. Closwap operates a peer-to-peer clothing swap platform, combining a digital marketplace with community events and gamified incentives designed to make swapping as effortless as buying new. Circular Way and its retail arm Stilbaar have created what they describe as the world’s first fully circular fashion store, buying back every garment sold and either refurbishing it or sending it to specialist recyclers. HURR offers a full-stack rental solution, handling returns, cleaning, repairs, and customer support for both individual lenders and retail partners including Selfridges.
What distinguishes these businesses from the circular initiatives of established brands, such as Patagonia’s Worn Wear, Levi’s SecondHand, Burberry’s ReBurberry, is not just scale but structure. For an incumbent, circularity can remain a peripheral activity alongside a predominantly linear operation. For a born-circular venture, the ability to recover, move, repair, and recirculate garments is the business model, not an addition to it. Logically, these businesses should be piggybacking on London’s circular infrastructure, amplifying the city’s ambitions while the city’s systems amplify their reach. What we found instead was near-total disconnection.
The City as Urban Metabolism
A useful way to understand this disconnection is to think of the city not as a backdrop for economic activity but as a complex system of interacting material flows – what urban systems theorists call an “urban metabolism”. In a functioning circular metabolism, materials flow through the city in closed loops, like oxygenated blood circulating through an organism and returning to be replenished. Businesses are organs within that system, contributing to and drawing from the flows around them.
The problem is that circular startups are currently operating as failed implants rather than organs, inserted into the urban body but not connected to its circulatory system. They create micro-metabolisms, circular loops that function at the level of the individual firm but remain adjacent to, rather than integrated with, the wider urban system.
As Joanna Williams, Professor of Sustainability at UCL and a leading authority on circular city transition, argues, a truly circular city cannot be reduced to the sum of its circular businesses.9 Cities must grapple with land use, infrastructure access, and social equity, questions that firm-level circular frameworks were never designed to answer. Cities represent entire economic systems of producers, consumers, infrastructure, and institutions; firms are organised around producing a defined set of outputs. What cities and firms must do to transition to circularity are two quite different things. Yet cities cannot be truly circular if businesses cannot plug into their circular plans, and born-circular businesses cannot scale if they are left to replicate urban infrastructure at private cost.
Three Blockages in the Circular Flow
Approximately 82,100 tonnes of second-hand clothing are collected in London annually, of which less than 10 per cent is reused locally, with the majority being exported overseas, entering global waste streams rather than local circular loops.10 Our analysis identified three structural reasons for this. While the specific case we examined was about clothing, the underlying dynamics are not sector-specific, and have implications for circular businesses beyond fashion.
Temporal misalignment. Circular startups operate on compressed timescales: quarterly targets, weekly inventory decisions, 24-hour delivery cycles. City strategies, planning decisions, and long-term service contracts move on a different clock entirely. As Closwap co-founder Maria Remy put it: “We can prototype a feature in weeks, but securing city support for a borough-wide collection pilot takes years.” Early-stage firms work with limited capital and cannot wait for the surrounding system to catch up. By the time public infrastructure becomes available, the business model or market opportunity may have moved on.
Infrastructural disparities. London’s supporting infrastructure is uneven and fragmented across its 32 boroughs. Standardised collection points, shared sorting facilities, and coordinated repair hubs do not exist at city scale. In their absence, businesses build their own parallel mini-systems rather than plugging into shared infrastructure, raising costs, duplicating effort, and concentrating services in the affluent, well-connected neighbourhoods where courier networks and cleaning services already cluster. Circular Way’s Sandrine Kockum aims to buy back 100 per cent of the clothes she sells; the infrastructure to connect repair businesses, collection systems, and textile recyclers in a coherent loop does not yet exist across the city.
Governance gaps. Circular businesses navigate regulatory systems designed for linear ones. UK VAT applies a 20 per cent rate to repair services, making fixes more expensive than replacements and undermining one of the core value propositions of the circular model. Extended Producer Responsibility frameworks focus on manufacturers, not circular intermediaries; HURR operates entirely outside EPR frameworks, with no targeted incentives or tailored regulations for rental models. Each of London’s 32 boroughs applies its own rules, meaning a business attempting to operate across the city faces 32 different regulatory environments rather than a unified urban market.
When the City Becomes Part of the Business Model
For entrepreneurs building circular businesses, the city is part of the operating architecture of the business model itself. This becomes most visible when circular businesses attempt to scale.
Conventional expansion logic assumes that a proven model can be standardised and transferred: enter a new market, adapt to local demand, grow. Circular businesses face a different challenge. Their operations may depend on collection systems, repair capacity, reverse logistics, material access, and institutional relationships that sit outside the firm’s direct control. A company can transfer its brand, technology, and internal processes, but the place-based capabilities that make its circular model work are harder to move.
Conventional expansion logic assumes that a proven model can be standardised and transferred: enter a new market, adapt to local demand, grow.
The degree of this dependency varies by model. A circular denim company like MUD Jeans can serve new markets through e-commerce, standardised product design, and a centralised take-back system, making it relatively less reliant on city-specific infrastructure. Repair, rental, and local recovery businesses are more closely tied to local labour, logistics, and processing capacity. Entering a new city may require assembling an entirely new network of service providers, commercial partners, and public institutions.
The United Repair Centre (URC), established in Amsterdam through collaboration between Makers Unite, Patagonia, and the Amsterdam Economic Board, offers a live test of this dynamic. Repairing over 29,000 items for more than 30 retail brands in 2024, it has since expanded into London and Paris. Brand relationships, operating knowledge, and service standards may travel with the firm, but skills pipelines, institutional access, and local infrastructure often need to be rebuilt from scratch in each new city. The cost of recreating local repair capacity and institutional relationships frequently becomes clear only once operations begin, making city choice a strategic decision rather than a market entry question.
This logic extends beyond fashion. Wherever a circular business model depends on local material flows, whether in food recovery, electronics refurbishment, or construction material reuse, the surrounding city’s infrastructure, governance, and institutional conditions shape whether the model can operate and scale. The specific blockages will differ by sector. The underlying dynamic is similar.
What Two European Cities Suggest About the Fix
The evidence from Amsterdam and Copenhagen suggests that the blockages identified in London, including the scaling challenge, are failures of design rather than inevitable features of urban circular transition.
Amsterdam’s commitment is paired with institutional and financial architecture. Its Circular Economy Strategy treats infrastructure for sharing platforms, second-hand businesses, repair services, and resale markets as strategic priorities. The city runs a live Circular Economy Monitor tracking material flows across 24 product groups, which found that 78 per cent of Amsterdam’s CO₂ emissions are linked to material use, a finding that directly shaped its investment priorities.11 The Amsterdam Circular programme, run in partnership with the AMS Institute and venture accelerator Rockstart, provides equity-free support to circular startups and connects them with over 1,500 co-financiers, using patient capital instruments designed for the long time horizons circular businesses require. As the programme’s lead Guy Vincent has noted, circular companies are building over a long time horizon that often does not align with conventional venture capital expectations.12 Amsterdam has not solved the firm-city gap, but it has named it and begun building toward it. Its patient capital model also speaks directly to the scaling problem: by supporting circular firms with financing built for long horizons and local partnerships, rather than conventional venture timelines, it lowers the cost of rebuilding place-based capabilities city by city.
Copenhagen has taken a complementary approach, focused on standardisation as the mechanism for closing the temporal gap. Its Circular Copenhagen plan mandated uniform waste sorting into 10 fractions across all households and committed to installing up to 750 new waste-sorting stations across the city.13 More significantly, it has developed a model for converting local experiments into binding shared infrastructure. Municipal pilots on textile waste collection and selective demolition generated evidence that was subsequently codified into national standards: Denmark mandated door-to-door household textile waste collection in 2023, ahead of the EU’s own requirement, directly on the basis of Copenhagen’s pilot data.14 Rather than waiting for startups to adapt to slow-moving public systems, the city accelerates the conversion of fast-moving local experiments into durable shared infrastructure that all businesses can use, which is precisely the kind of transferable groundwork that makes scaling into a new city less like starting from zero.
What Needs to Happen
The opportunity is substantial. The World Economic Forum estimates a $1 trillion annual global benefit from circular transition. Localised material loops reduce transportation costs, provide predictable feedstock for manufacturers, generate employment in repair and recovery, and insulate cities from volatile global supply chains.
For cities, declaring circular ambitions is not enough. What Amsterdam and Copenhagen are doing differently is redesigning the conditions for circular activity: building shared infrastructure, standardising systems, and aligning capital instruments with circular time horizons, rather than simply setting targets and waiting for the market to respond. However, it is worth noting that research evaluating Amsterdam, Copenhagen, and Glasgow’s circular plans raise questions about the inclusiveness and access to infrastructure of the former two.15 If left unaddressed, these will impede the path to circularity. London’s top ranking in the Circular Cities Barometer reflects its performance in construction waste and sustainable mobility. This masks a fundamental struggle to build the enabling infrastructure that born-circular businesses in textiles, food, and electronics most urgently need. A city’s circular credentials should ultimately be measured not just by what it collects and recycles, but also by how well its systems allow circular businesses to connect, operate, and scale.
For entrepreneurs, the most practical route for now is to build models that align with the infrastructure that does exist: courier networks, community repair groups, borough-level pilots, textile recyclers. Treating integration as a design principle from the outset, rather than a final step once scale is reached, is the difference between a circular business that grows with the city and one that grows beside it.