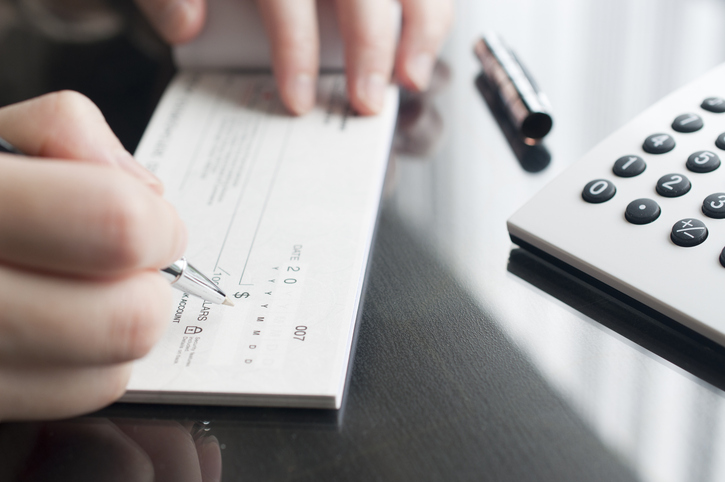
Managing high-volume payments is an everyday reality for corporate banking teams. Picture a finance manager overseeing hundreds of monthly supplier disbursements, payroll runs, and reimbursement cycles. Each payment demands reliable, secure, and regulation-compliant documentation. Selecting between generic business cheques and those tailored by a major financial institution like Bank of Montreal determines not just the efficiency of these processes, but also their safety against fraud and error. The right cheque solution addresses compatibility with accounting software, bank compliance, and advanced security needs—essentials when the stakes include both large sums and sensitive data. Comparing Bmo Order Cheques and standard business cheques reveals practical differences that shape how corporate accounts handle risk and operational flow.
Evaluating Corporate Banking Stationery Needs
Every high-volume corporate account has unique requirements for cheque issuance, including compatibility with accounting systems, regulatory compliance, and bulk order efficiency. For example, firms using enterprise resource planning (ERP) software often need cheques formatted to print accurately from their system, without manual intervention or risk of misalignment. In this context, banking stationery becomes more than a commodity—it’s a tool for operational control and audit trail accuracy.
Many businesses also face internal mandates for multi-level approval workflows, which demand cheques that support features like pre-printed signatures or secure paper stock. These requirements go beyond basic payment needs, directly influencing which form of stationery—standard or bank-specific—fits best. Understanding corporate cheque printing standards is fundamental before deciding which product to adopt.
Ultimately, a company’s volume and process complexity shape the ideal solution. A small business may meet its needs with standard cheques, but larger enterprises often require the higher degree of customization and security that bank-issued stationery provides.
Comparing Standard Business Cheques and BMO Options
Standard business cheques, available from office suppliers, offer generic formats that suit basic payment needs. These forms can be compatible with popular accounting software but may not always align with a specific financial institution’s latest requirements. In contrast, BMO’s stationery is designed to meet its proprietary standards, ensuring seamless deposit, withdrawal, and reconciliation processes for corporate customers.
When companies compare Bmo Order Cheques business banking users benefit from, they find that these products often include compatibility with BMO’s processing systems, updated security marks, and layout options that match bank requirements. For example, using Bmo Order Cheques ensures each cheque meets the bank’s format and security guidelines, reducing clearance delays and potential errors. This option provides enterprises with a consistent, bank-verified tool for high-frequency transactions.
Choosing between generic and institution-specific cheques comes down to the balance between flexibility and guaranteed acceptance. For organizations with multiple accounts at BMO, using the bank’s own stationery can streamline end-of-month reconciliation and help avoid manual correction costs.
Security Features Protecting High-Volume Accounts
For large organizations, cheque fraud is a tangible threat. Bank-specific stationery, like the forms produced for BMO clients, incorporates proprietary anti-fraud features such as microprint borders, watermarks, and chemical-sensitive paper. These elements make unauthorized replication or alteration much more difficult, deterring both opportunistic and targeted attacks.
Standard business cheques may offer basic security features, but these are often generic and widely known, making them easier to compromise. In contrast, bank-issued cheque stock is updated regularly to address emerging threats and incorporates security elements that align with the bank’s internal verification systems. Understanding the cheque fraud prevention measures integrated into your stationery is essential for safeguarding large transaction volumes.
For corporate accounts managing substantial cash flows, prioritizing advanced security features reduces exposure to financial loss, reputational damage, and compliance headaches. This is a key reason why many high-volume businesses standardize on institution-issued stationery.
Choosing the Right Cheque Solution for Your Enterprise
Determining the optimal cheque product begins with a close review of existing payment workflows and risk management strategies. Organizations processing thousands of payments monthly should assess whether their current stationery matches the technical requirements and security benchmarks set by their primary bank. This includes verifying that cheque layouts support automated clearing and are compatible with internal accounting and payroll systems.
Large enterprises often benefit from working directly with their bank or authorized providers to customize cheque features—such as incorporating multiple signature lines, custom backgrounds, or security holograms. While standard business cheques may suffice for smaller operations, high-volume corporate accounts are best served by options that offer both compliance and security assurances.
Reviewing how you compare Bmo Order Cheques business banking needs with available alternatives ensures that your choice addresses not only cost but also fraud risk and operational efficiency. The most effective solution is one that supports your organization’s growth while minimizing vulnerabilities in your payment process.
Conclusion
Start by auditing your current cheque processes for compliance and security gaps. If your high-volume corporate account demands advanced fraud protection, seamless integration, and reliable bank acceptance, institution-specific stationery is often the best fit. Consult with your financial institution or an experienced supplier to match your payment volume and risk profile to the right cheque solution.